
Bond yield explosion gives Bitcoin a strong signal – is now finally Satoshi’s time?
Bitcoin’s monetary case is growing stronger as governments face more expensive borrowing, and software is becoming a buyer of services. Sovereign financing pressure gives people a reason to consider money issued outside government policy. Agent commerce gives that money another way to circulate.
The Bank of England put sovereign-bond stress and the borrowing that finances artificial intelligence in the same warning on September 30. Its financial-stability record describes an extended energy shock pushing government yields higher, while growing AI-related debt leaves more investors exposed to the technology’s fortunes.
I see a credible catalyst for hyperbitcoinization in that combination. A transition toward Bitcoin as widely used money would require people and businesses to hold it, spend it and price services in it. If they retain bitcoin for future purchases, more payment utility could reinforce demand for the balance itself.
On the same day as the Bank’s warning, Mastercard announced new trust and intelligence services for its Agent Pay program, including a score designed to identify AI-initiated transactions. That score is rolling out for testing in the United States.
September’s developments bring a widening financial-risk debate together with an active race to serve software customers. Bitcoin has a route into that race through tools built earlier this year; established payment companies are preparing to serve the same buyers.
Higher yields sharpen Bitcoin’s argument and its competition
The pressure is visible in the cost of government borrowing. CryptoSlate’s 10-year Treasury series displays a September 30 daily par yield of 5.29%. The Fed’s September 30 release reports 5.26% for September 29. The observations describe different days and should be compared on that basis.
The policy backdrop is also tighter in important places. The Fed raised its target range by a quarter of a percentage point to 3.75%–4% on September 16, under Chair Kevin Warsh, who took office May 22. The Bank of Japan set its overnight call-rate guideline at around 1.25% on September 18, effective September 24.
The Bank of England held Bank Rate at 3.75% in its September 17 announcement, although three policymakers wanted an increase to 4%. Market yields can tighten financing conditions even when a central bank leaves its policy benchmark unchanged.
Higher yields create two competing effects for Bitcoin. They make the long-term cost of financing government debt more conspicuous, which can strengthen interest in money whose issuance is independent of a government’s borrowing needs. They also offer investors a higher contractual return for holding bonds, raising the hurdle for an asset that pays no native interest.
Investors still have to weigh a bond’s contractual income against inflation and their time horizon. Bitcoin’s capped supply governs how many coins can exist; demand determines their purchasing power. The tension between income and independently issued money already examined in CryptoSlate’s bond-market coverage remains central.
Bitcoin traded at roughly $83,530 near press time, after reaching both a new all-time high of $125,000 and a low of $57,500 over the last 12 months. That volatile price can reflect many sources of demand. The monetary argument has to stand on how people hold and use bitcoin as well as what they pay for it.
The same Bank assessment described a financial system that had remained resilient, with mostly gradual market adjustments. That is the backdrop for the bullish argument: financing pressures can make independent issuance more attractive even while existing institutions continue to function.
Satoshi Nakamoto’s whitepaper begins with electronic payments sent directly between parties without going through a financial institution. Its solution replaces a trusted intermediary’s double-spending checks with a peer-to-peer network and proof of work, subject to the design’s security assumptions.
Its design gives Bitcoin a different relationship with authority. Its issuance does not expand because a government needs to refinance debt or a central bank decides the economy needs additional support. Under the protocol’s existing rules, issuance moves toward a maximum of 21 million bitcoins.
Someone seeking money outside a particular issuer’s policy decisions can choose an asset with an independently verifiable supply rule. Market volatility and custody responsibility remain the cost of that choice.
Bitcoin cannot remove an energy shortage or make borrowed capital cheap. It can offer a monetary asset whose issuance is separate from the institutions managing those problems. Treating that property as valuable is a coherent position even when higher interest rates make the asset less attractive in the short term.
Agents give Bitcoin a practical route into commerce
An AI agent cannot hand over a banknote. It can request data, receive an invoice, authorize a payment and continue its task. For commerce to work, that transaction needs little overhead, clear spending authority and reliable settlement.
Bitcoin has concrete infrastructure for that pattern. In February, Lightning Labs released agent tools that let software pay for APIs through L402, a protocol combining Lightning payments with access credentials. An API can request payment, the agent pays a Lightning invoice, and payment unlocks the resource.
This gives Bitcoin utility beyond an investor buying and waiting. A software buyer can pay for a piece of data at the point it needs it, instead of having a person arrange another subscription. A service provider can charge for individual requests. Lightning supplies the payment layer that makes small, repeated Bitcoin transactions practical.
Lightning Labs also announced Wavelength in July, an alpha toolkit intended to make wallet integration easier for developers and agents. At launch, it was open on test networks with mainnet access by invitation. Broad commercial adoption would require developers and customers to put that infrastructure to use.
Security is a design requirement here. The documented tools use measures such as remote signing, restricted credentials and spending limits; Wavelength says wallet creation and unlock keep seeds and passwords outside the agent channel. Those controls can reduce what a model can expose or spend. Intelligence alone does not make an agent a safer custodian than a human.
An agent should receive enough authority to pay for its task without receiving unrestricted access to its owner’s savings. A useful machine economy needs bounded financial authority as much as it needs faster reasoning.
Software buyers already have several other ways to pay.
Google’s AP2 framework, announced in September 2025, supports cards, stablecoins and bank transfers, using signed mandates to record what a user authorized. Coinbase’s September 22 agent announcement adds equities trading and x402 micropayments for data, models and services within user-defined limits. Mastercard’s latest testing builds another path inside established payment relationships.
For an agent buying a dollar-priced service, a dollar-linked balance can simplify budgeting. A business paying expenses in dollars may prefer to receive dollars too. As CryptoSlate’s recent stablecoin coverage explored, the rise of software buyers can extend digital-dollar use rather than displace it.
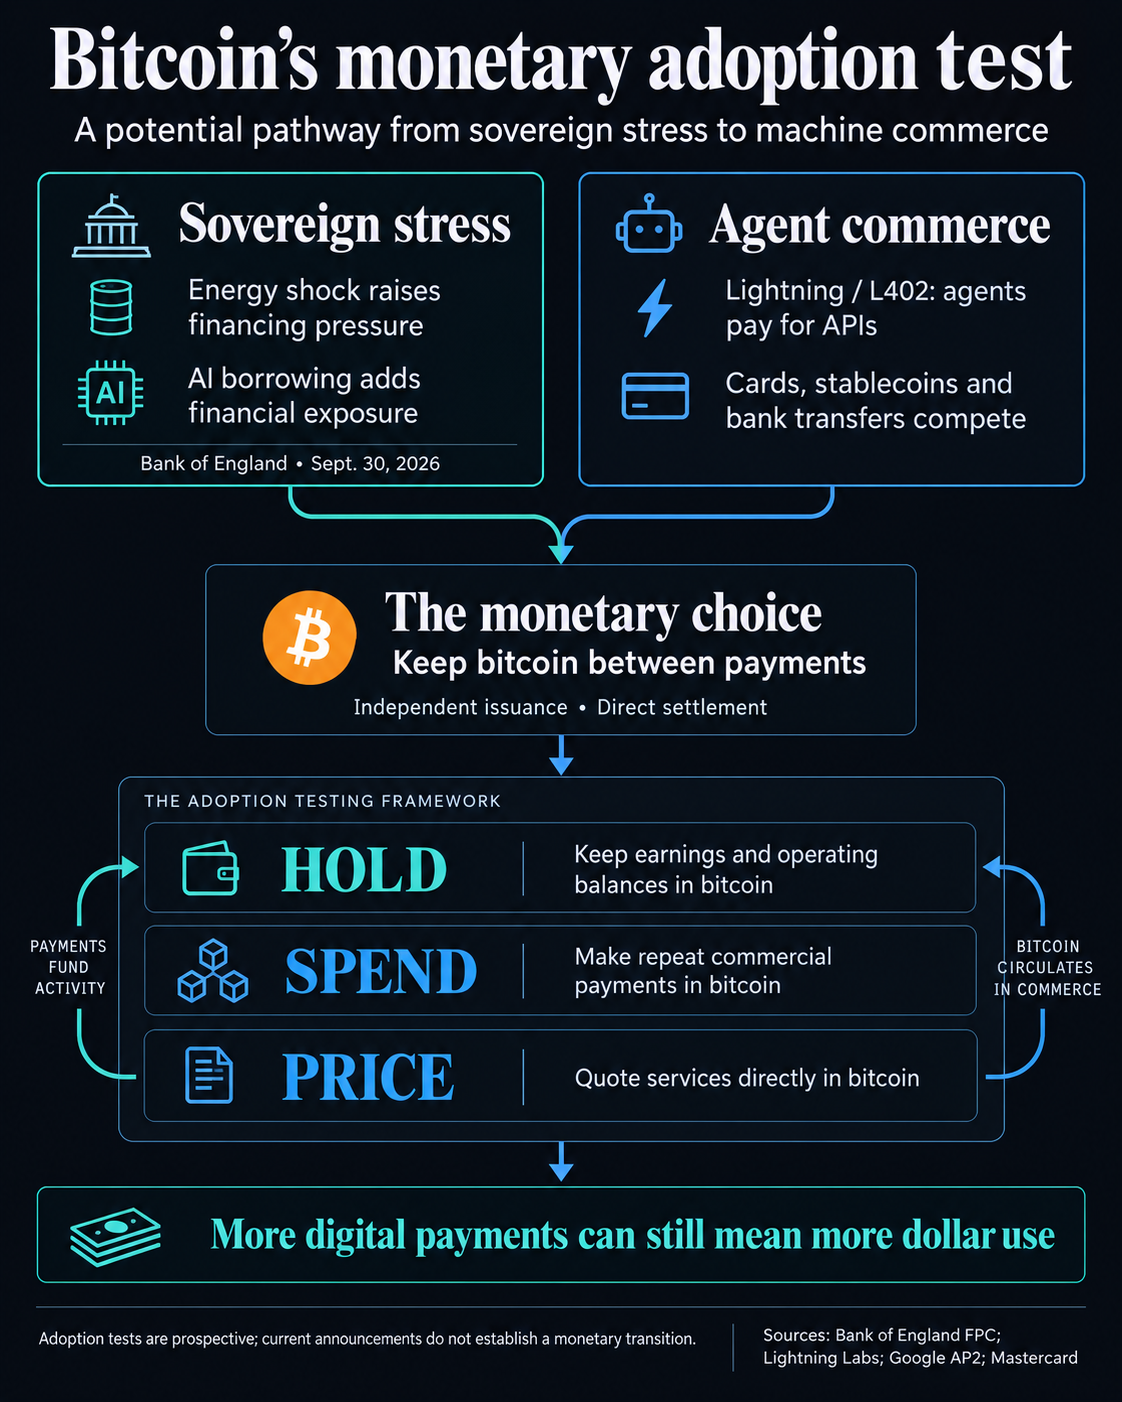
Bitcoin’s distinctive opportunity lies in the users who value independently issued money and direct settlement enough to retain bitcoin between transactions. An agent that briefly converts a dollar balance into bitcoin to make a payment demonstrates useful infrastructure. An agent or business that earns, holds and spends bitcoin demonstrates a deeper monetary choice.
Those choices may coexist. Bitcoin could become more useful for saving and settlement while dollars remain common for pricing everyday services. That would be meaningful progress for Bitcoin without meeting the stronger definition of hyperbitcoinization.
The catalyst is credible; the adoption test is concrete
Sovereign stress supplies a reason to reconsider what money people hold. Agent commerce supplies a way for digital money to circulate with less human administration. Together they give Bitcoin a more substantial opportunity than a narrative built only around the next rate decision.
AI can also intensify the financing problem. The Bank of England warns that debt-funded AI investment expands financial exposure and that disappointment in expected productivity gains could reach sovereign markets. The technology creating new payment users is being built within the same credit system Bitcoin offers an alternative to.
That is why I am bullish about Bitcoin’s monetary role. A reason to hold bitcoin and more ways to use the balance could reinforce each other. Turning that opportunity into adoption will depend on the choices people and businesses make.
The signs of that shift would be repeat commercial payments in bitcoin, recipients keeping part of their earnings in bitcoin, operating balances held in bitcoin and services priced directly in it. Those behaviors would move the argument beyond payment announcements and into monetary adoption.
If agents mainly spend stablecoins or authorized card balances, machine commerce will have modernized fiat. If businesses and their software start retaining and pricing value in bitcoin, the monetary transition will have a firmer foundation. Bitcoin’s opportunity grows when its users choose to keep the money they can now move.
The post Bond yield explosion gives Bitcoin a strong signal – is now finally Satoshi’s time? appeared first on CryptoSlate.